
A personal loan can be a useful way to spread the cost of a major purchase, consolidate existing borrowing or cover an unexpected expense. But choosing a loan based only on the headline interest rate can be expensive.
For UK households, the real cost of borrowing depends on several factors, including the APR, loan term, monthly repayment, fees, eligibility criteria and whether the rate shown is actually the rate offered.
Before applying, it is worth comparing the full borrowing picture rather than focusing on a single number.
Consumers researching their options can use WiT Money’s personal loan comparison to review different UK borrowing options and understand how lenders may differ.
1. Compare the Representative APR
The representative APR is one of the first figures borrowers tend to look at.
APR stands for Annual Percentage Rate. It is designed to show the annual cost of borrowing, taking into account interest and certain fees.
However, there is an important point to understand:
The representative APR is not necessarily the rate every applicant will receive.
UK lenders can advertise a representative APR if at least 51% of successful applicants are expected to receive that rate or lower. That means a significant proportion of borrowers may be offered a higher rate.
Your actual rate may depend on factors such as:
- credit history
- income
- existing debts
- loan amount
- loan term
- affordability
- lender risk assessment
So while representative APR is useful for comparison, it should not be treated as a guaranteed borrowing rate.
2. Compare the Total Amount Repayable
Monthly repayments are important, but they do not tell the whole story.
A longer loan term can reduce the monthly payment while increasing the total amount of interest paid over the life of the loan.
For example, borrowing £10,000 over three years will usually result in higher monthly payments than borrowing the same amount over five years.
However, the five-year loan may cost substantially more overall because interest is being charged for longer.
Borrowers should compare:
amount borrowed + total interest + applicable fees = total amount repayable
This figure often provides a clearer indication of the true cost of the loan.
3. Compare Loan Terms Carefully
The loan term determines how long you will be making repayments.
Common personal loan terms may range from around one year to seven years or more, depending on the lender and borrowing amount.
A shorter term can mean:
- higher monthly repayments
- less interest paid overall
- faster repayment of the debt
A longer term can mean:
- lower monthly repayments
- greater total interest
- debt remaining for longer
The right balance depends on household cash flow.
A loan repayment should be affordable without leaving so little disposable income that another unexpected expense creates financial difficulty.
4. Check Whether the Monthly Payment Is Realistically Affordable
A lender’s willingness to approve a loan does not automatically mean the repayment is comfortable for your household budget.
Before borrowing, consider regular expenses such as:
- mortgage or rent
- council tax
- energy bills
- food
- transport
- childcare
- insurance
- existing credit commitments
- savings contributions
It can also be useful to test what would happen if household income temporarily fell or essential costs increased.
The best loan is not necessarily the one offering the largest amount. It is often the one that fits comfortably within your existing finances.
5. Compare Eligibility Before Making Multiple Applications
Applying for several loans in a short period can potentially result in multiple hard searches appearing on your credit file.
For that reason, borrowers may want to use eligibility checkers or quotation tools where available before submitting full applications.
A soft credit check can usually provide an indication of eligibility without leaving the same type of visible footprint as a full application.
This can help households identify potentially suitable lenders before making a formal application.
Borrowers with previous credit problems should be particularly careful about making repeated applications.
Consumers in this position can also review bad credit loan options through WiT Money to understand the types of borrowing available and how rates may differ for applicants with weaker credit histories.
6. Compare Fees and Early Repayment Terms
Not every personal loan has significant upfront fees, but borrowers should still review the lender’s terms carefully.
Things to check include:
- arrangement fees
- administration charges
- late-payment fees
- missed-payment charges
- early repayment conditions
Some borrowers plan to repay a loan ahead of schedule if their financial situation improves.
Early repayment can reduce future interest, but lenders may be entitled to charge limited compensation in certain circumstances.
Always check the loan agreement before assuming there is no cost to settling early.
7. Compare Fixed and Variable Interest Rates
Many UK personal loans use fixed interest rates.
A fixed-rate loan means the interest rate normally remains unchanged throughout the agreed term, providing predictable monthly repayments.
Variable-rate borrowing can change over time, meaning repayments or borrowing costs may increase.
For households prioritising budgeting certainty, a fixed rate may be easier to manage.
Regardless of the rate structure, borrowers should understand whether repayments could change during the loan period.
8. Consider the Purpose of the Loan
A personal loan can be used for many different purposes, but it is worth asking whether borrowing is appropriate for the expense.
Common uses include:
- home improvements
- buying a vehicle
- consolidating debts
- weddings
- large household purchases
- unexpected repairs
Borrowing for an asset or necessary expense may be easier to justify than borrowing for everyday spending.
If a household regularly needs loans or credit to meet normal monthly expenses, taking another loan may simply postpone a broader affordability problem.
9. Be Careful With Debt Consolidation
Debt consolidation can make finances easier to manage by replacing several repayments with one loan.
It may also reduce interest costs if the new loan has a lower effective borrowing rate.
However, consolidation is not automatically cheaper.
- outstanding balances
- current interest rates
- remaining repayment periods
- new loan APR
- total amount repayable
- fees
A lower monthly payment can sometimes be achieved simply by extending the debt over a longer period, which may increase the overall cost.
Debt consolidation works best when borrowers understand the full repayment impact and avoid rebuilding balances on the credit accounts that have been cleared.
10. Understand How Credit History Affects the Offer
Lenders use credit information as part of their assessment process.
A stronger credit profile may give a borrower access to a wider range of lenders and potentially lower rates.
Applicants with missed payments, defaults, county court judgments or limited credit history may have fewer choices and face higher borrowing costs.
This is one reason comparing lenders matters.
Different lenders have different risk criteria, so a borrower who does not fit one lender’s model may still be considered by another.
However, borrowing at a very high APR should be approached cautiously because the total repayment burden can become substantial.
11. Compare Personal Loans With Other Forms of Credit
A personal loan is not always the most appropriate financing option.
Depending on the amount and purpose, alternatives may include:
- 0% purchase credit cards
- balance transfer cards
- overdrafts
- savings
- secured borrowing
- retailer finance
For example, a credit card offering a genuine interest-free purchase period may cost less than a loan if the balance can be fully repaid before the promotional period ends.
However, credit cards can become expensive if balances remain after promotional rates expire.
The important point is to compare the total cost and repayment structure rather than assuming one type of borrowing is always better.
12. Check Whether the Lender Is Properly Authorised
Borrowers should also check who they are dealing with.
Most firms offering consumer credit in the UK are required to be authorised or registered with the Financial Conduct Authority, depending on their activities.
Consumers should be cautious about:
- requests for unusual upfront payments
- guaranteed loan claims
- unsolicited loan offers
- pressure to transfer money quickly
- lenders that cannot clearly explain their regulatory status
A legitimate comparison process should help borrowers understand the lender and product before proceeding.
What Should Households Prioritise?
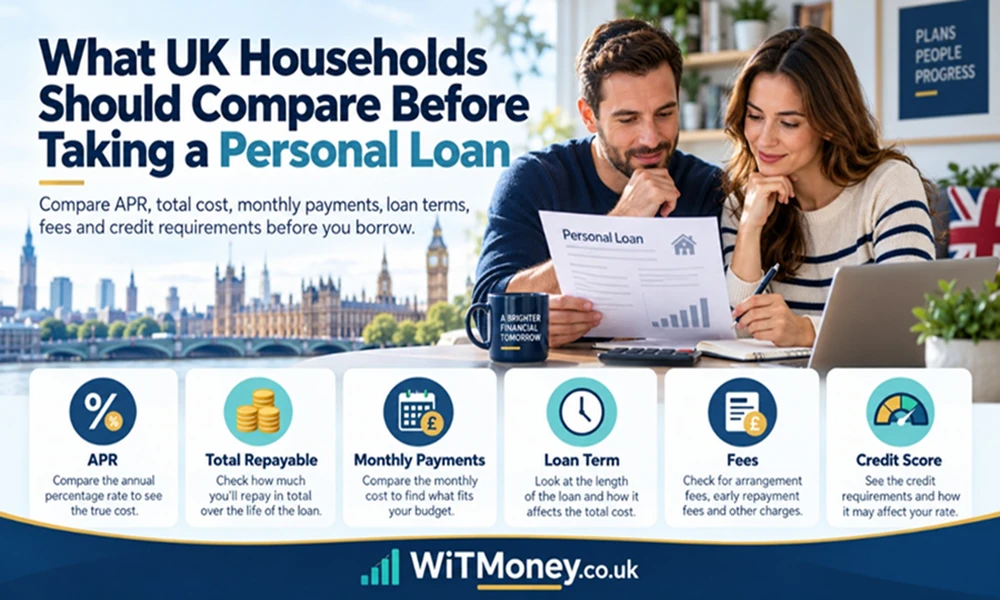
When comparing personal loans, UK households should focus on the combination of:
APR
total amount repayable
monthly repayment
loan term
eligibility
fees
flexibility
affordability
No single figure tells you whether a loan represents good value.
A low advertised APR is not especially useful if you do not qualify for it, and a low monthly payment may be misleading if the loan lasts much longer and costs considerably more overall.
Final Thoughts
Taking a personal loan is a significant financial commitment, particularly when household budgets are already under pressure.
Before applying, borrowers should compare more than just the headline rate. Understanding the total repayment, repayment period, monthly affordability, eligibility requirements and potential charges can make it easier to choose an appropriate option.
Those considering borrowing can explore personal loans available to UK consumers through WiT Money.
Applicants with previous credit difficulties can separately review UK bad credit loan comparisons to understand how specialist borrowing may differ in cost and eligibility.
Taking time to compare the full cost of borrowing can help households avoid choosing a loan that looks affordable initially but becomes unnecessarily expensive over the longer term.